Feb 6
The Brazil sugar industry stands as one of the most influential sectors in the global agricultural economy. Known for its vast sugarcane plantations and advanced production techniques, Brazil has become a leading exporter of sugar and ethanol. This blog post explores the dynamics of Brazil's sugar industry, its economic impact, sustainability efforts, and future prospects.
How large the sector is, and where to get a number you can cite
Brazil is the world's largest exporter of sugar. Its favourable climate, extensive arable land and mechanised production have made it the origin most bulk buyers default to, and cultivation is concentrated in the Centre-South — São Paulo, Minas Gerais, Goiás and Paraná — with a second, smaller industry on the North-East coast running on the opposite calendar. Share-of-trade percentages are widely quoted for Brazil and rarely sourced; if you need one for a commercial decision, take it from a recognised balance sheet such as the International Sugar Organization's rather than from a supplier's website. What is not in dispute is the ranking: no other origin exports more — how Brazil compares with India, Thailand, Australia and the rest sets out what each origin offers a buyer. The five centuries behind that position explain how it was reached. How sugar is actually manufactured in Brazil covers the production side, and the two crop calendars explain why the season matters to a buyer.
The sugar industry in Brazil is not only vital for domestic consumption but also plays a crucial role in international trade. The industry supports millions of jobs, from farming and processing to logistics and export operations. Brazil's sugarcane is processed into raw sugar, ICUMSA 45 refined white sugar, and ethanol, making it a versatile commodity.
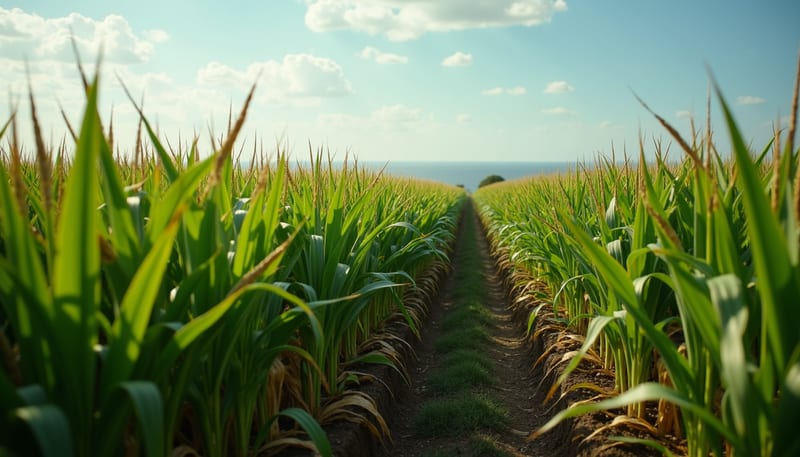
Sugarcane fields in Brazil's southeastern region
Sugarcane plantations in São Paulo state, Brazil
Economic Importance and Export Markets
Brazil exports sugar to Asia, Africa, the Middle East, Europe and the Americas. Access to each of those markets is governed by its own tariff and quota regime rather than by a single global rule — the United States, for instance, admits sugar under a tariff-rate quota, and Arab-League destinations price it off the preferential certificate of origin. Where Brazilian sugar goes and what each destination requires sets those out.
The other half of the equation is ethanol. Because most Brazilian mills can direct juice to sugar or to ethanol depending on returns, supply is responsive to price rather than fixed by planting — which is why Brazil remains the origin most bulk buyers default to for volume.
Why the sustainability record is also a cost record
Most of what the Brazilian sector reports as environmental performance is, read commercially, cost engineering — which is why it is durable rather than cyclical. Cogeneration is the clearest case: burning bagasse, the fibre left after crushing, to raise steam and electricity makes a mill's process energy internal rather than purchased. That shows up as a lower energy line on the income statement and as a lower carbon intensity in a customer's reporting, from the same decision.
Where a destination market requires a sustainability scheme certification, ask for the certificate with its number and issuing body — no certification is claimed on this site.
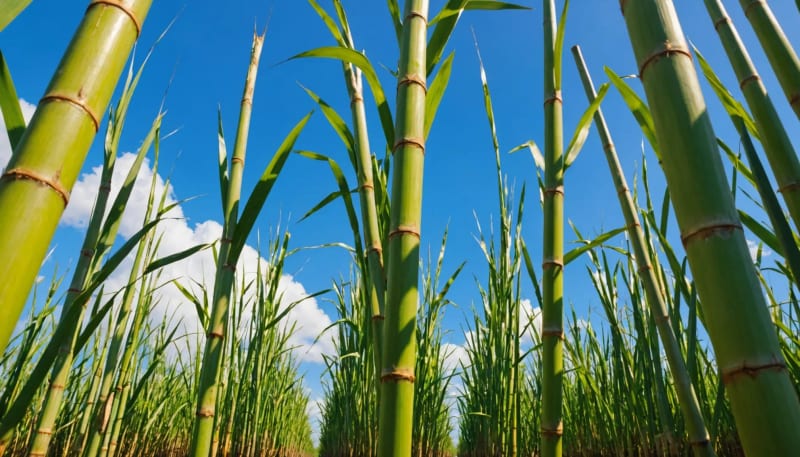
Sugarcane stalks in a Brazilian plantation
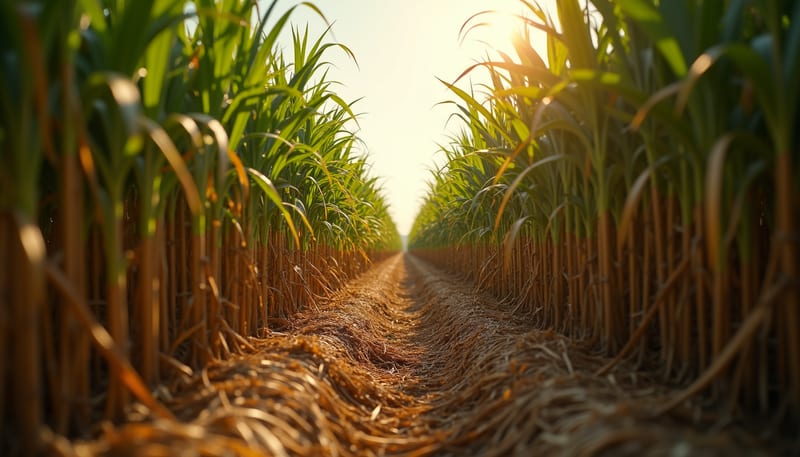
Sugarcane ready for harvest in Brazil
The four exposures that move Brazilian sugar economics
Four exposures account for most of the variation in Brazilian sugar economics, and all four reach the buyer as a change in the quotation rather than as news.
Weather. Cane yield is a rainfall and frost story. Drought during cane development or unseasonal rain during the crush both reduce recoverable sugar per tonne of cane, and because Brazil is the largest exporter the effect lands on the world benchmark rather than staying local.
Market volatility. The ICE No. 11 benchmark moves on supply from competing origins, demand shifts, and trade policy changes in importing countries. A buyer's landed cost changes with it.
Currency. Costs are incurred in reais and the cargo is sold in dollars, so BRL/USD moves a Brazilian seller's dollar cost base in both directions.
Labour and compliance. Mechanisation shifted the labour profile from field cutting to operating and maintaining equipment, and audited working conditions are now a procurement requirement for buyers supplying regulated markets, not only a regulatory one.
Where the sector's value is shifting
Three trends are changing what a Brazilian sugar cargo is worth and who buys it:
- Deeper by-product chains from bagasse and molasses, which make the mill's sugar line less exposed to sugar alone.
- Lot-level traceability, driven by regulated destination markets that require origin documentation down to the mill.
- Export diversification towards Asian and African destinations, which shifts the mix of grades, packaging and Incoterms the sector needs to offer.
In summary, Brazil's sugar industry remains a vital player on the global stage. Its combination of scale, grade flexibility across the full ICUMSA range and a long aggregate shipping season is what keeps it the default origin for bulk buyers. If you are sourcing rather than studying the sector, the practical starting points are how a sugar quotation is built and how to verify a Brazilian exporter before you contract.
For more detailed insights on Brazil's agricultural sectors, visit the Brazilian Ministry of Agriculture.
Recent Posts
The Ultimate Guide to Buy Sugar in Bulk: Smart Tips and Benefits
The Ultimate Guide to Wholesale Sugar Suppliers: How to Choose the Best Partner for Your Business
Unlocking the Potential of Sugar Wholesale: A Comprehensive Guide