Most sugar market commentary is written for traders. This one is written for the people who actually take delivery: procurement managers, food and beverage manufacturers, and distributors who need a specific ICUMSA grade, in a specific quantity, landed at a specific port. What follows is how the forces that move the world sugar price translate into the three decisions a bulk buyer actually makes, which grade to specify, when to contract, and what to verify before signing.
Why Brazil sets the tone
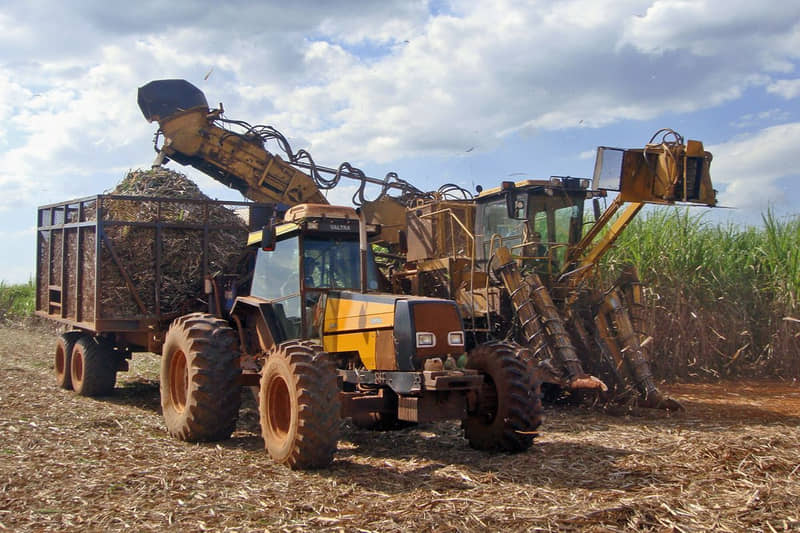
Brazil is the world's largest producer and exporter of sugar, so what happens in its Centre-South cane belt is felt in every other market. Two features of the Brazilian industry matter more to buyers than any other single factor.
The first is the sugar-ethanol switch. Brazilian mills are built to produce either sugar or ethanol from the same cane, and they move between the two depending on which pays better at the time. When ethanol economics are strong, less cane goes to sugar and export availability tightens. When sugar leads, mills swing back. For a buyer this means Brazilian supply is not a fixed quantity that responds slowly to demand. It can shift within a single season.
The second is the harvest calendar. The Centre-South crush runs from roughly April to November, with volumes building through the middle of the season. Contracting patterns, vessel availability and spot pricing all follow that rhythm, which is why the same enquiry can return very different numbers in May and in February. Brazil also has a second, smaller North-East crop running the other way — both are set out in the harvest calendar, and why the mills behave this way is structural rather than tactical.
What actually moves the price
Weather in the cane belt. Drought during cane development or unseasonal rain during the crush both reduce recoverable sugar per tonne of cane.
Ethanol parity. This sets the practical floor under how much cane is available for sugar at all.
The Brazilian real. A weaker real makes Brazilian sugar cheaper in dollar terms and encourages exports. A stronger one does the reverse.
Freight and container availability. On a low-value, high-volume commodity, logistics is a meaningful share of the landed price, not a rounding error.
Policy in other producing countries. Export restrictions or subsidy changes in India and Thailand redirect trade flows and change who is competing with Brazilian sugar in your market — what each exporting origin actually offers a buyer sets out the alternatives, and the United States admits sugar only under a tariff-rate quota rather than freely.
Turning market conditions into a grade decision
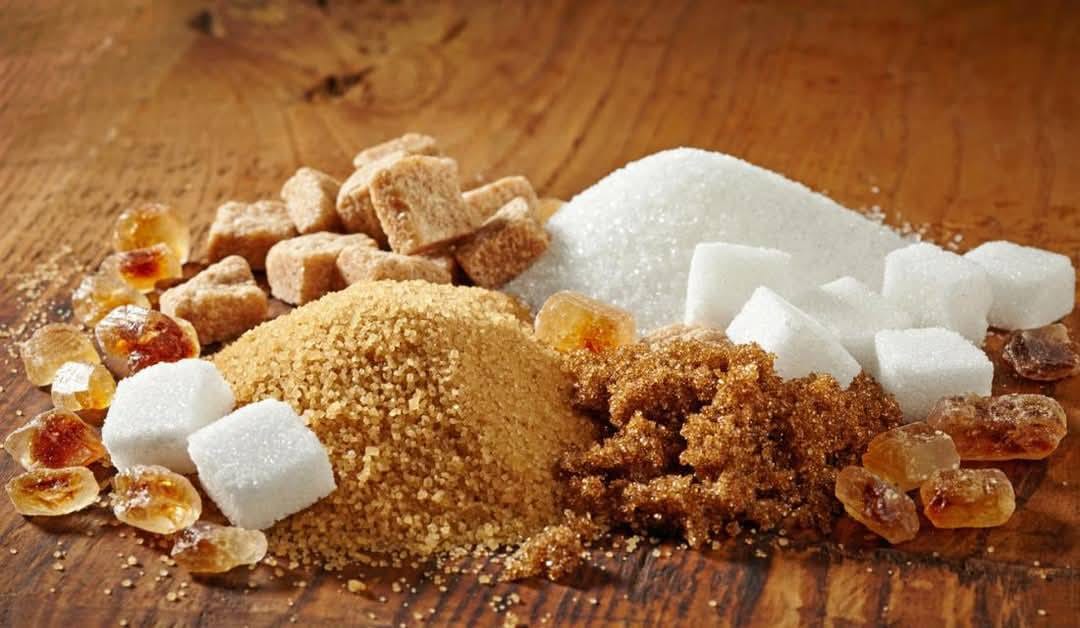
ICUMSA is a colour measurement, not a quality ranking. The lower the number, the more refining has been done and the whiter the sugar. Every stage of refining costs money, so in practice ICUMSA is a price ladder. The most common way buyers overspend is by specifying a whiter sugar than their process actually needs.
ICUMSA 45 is the highest-purity grade, for applications where colour and clarity are visible in the finished product: soft drinks, confectionery, pharmaceuticals and cosmetics.
ICUMSA 35 is an ultra-low-colour refined grade for premium food and beverage production.
Crystal white sugar is granulated refined sugar for bakery, dessert and beverage lines.
ICUMSA 100 is a mill-white grade that costs less than fully refined sugar and suits high-volume applications where a marginally higher colour is irrelevant.
Beverage-grade refined sugar is produced to soft-drink bottling specifications.
ICUMSA 600-1200 raw brown cane sugar is unrefined and retains part of its molasses layer. It is bought as refinery feedstock, as an input for fermentation and ethanol, and for industrial uses where colour does not matter.
If your finished product is dark, fermented, or further processed, paying for ICUMSA 45 is money spent on a specification your own customer will never see — and how brown and raw grades are specified and priced covers that end of the ladder. The ICUMSA colour scale and grade chart explains the scale itself, and which grade comes off which point of the refining line explains why the ladder exists.
Timing and contract structure
Because Brazilian availability moves with the crush and with ethanol economics, when you buy matters nearly as much as what you buy. Buyers who need continuity through the year generally split their volume: a term contract covering baseline demand, and spot purchases layered on top to take advantage of softer periods. Buyers with flexible storage can weight their purchasing toward the middle of the Centre-South season, when volumes are at their fullest.
Whatever the structure, agree the specification, the packing, the incoterm and the inspection regime in writing before price is discussed. Renegotiating a spec after a price is fixed is where most disputes start. The packaging decision itself — bags, jumbos, containers, breakbulk — is set out in the unit ladder, and how a quotation is assembled against the ICE No. 11 benchmark explains the number you will be given.
Sustainability and certification are now part of the specification
Sustainability has moved from a marketing line to a procurement requirement, particularly for buyers supplying European and North American brands. Two things come up repeatedly in tenders.
Certification. Bonsucro is the most widely recognised sustainability standard for sugarcane, covering environmental and labour criteria across the supply chain. Increasingly, buyers ask for it by name. Treat any supplier's certification claim the way you would treat a specification claim: ask for the certificate, with its number and its issuing body. This site makes no certification claim of its own.
Energy use at the mill. Brazilian mills commonly burn bagasse, the fibrous residue left after crushing, to generate their own power, which materially lowers the carbon intensity of the sugar produced. If your customers ask about embedded emissions, this is the detail worth knowing.
What to verify before you sign
Specification: ICUMSA range, polarization, moisture, ash, and granulation, stated as a range rather than a single number.
Documentation: certificate of analysis, phytosanitary certificate, certificate of origin, and any certification your own customers require.
Packing: bag weight and construction, palletisation, and container stuffing method.
Inspection: who appoints the surveyor, at which point, and whose result is binding.
Incoterm and port: which Brazilian port, and where risk and cost actually transfer. Who pays for what under FOB, CFR and CIF is the table to settle this against.
Counterparty: that the company exists, that it exports, and that it has the cargo. The supplier qualification checklist, how to verify a Brazilian exporter and the top sugar exporters in Brazil, and what each will actually sell you cover the checks.
Where this leaves buyers
The headline sugar price is the least useful number in a purchasing decision. What determines your landed cost is the grade you specify, the point in the Brazilian season at which you contract, and how tightly the specification and inspection terms are written. Buyers who get those three right routinely pay less than buyers reacting to price alone.
If you are sizing a requirement and want current availability, specifications or a quotation against a named port, contact us with your grade, volume and destination. If you are buying into a particular market, the UAE and South African routes have their own guides.
Recent Posts
The Ultimate Guide to Buy Sugar in Bulk: Smart Tips and Benefits
The Ultimate Guide to Wholesale Sugar Suppliers: How to Choose the Best Partner for Your Business
Unlocking the Potential of Sugar Wholesale: A Comprehensive Guide